Payments and Funds · Dubai Real Estate Guides
How to Pay for Property in Dubai
The Payment Playbook for Off-Plan and International Buyers
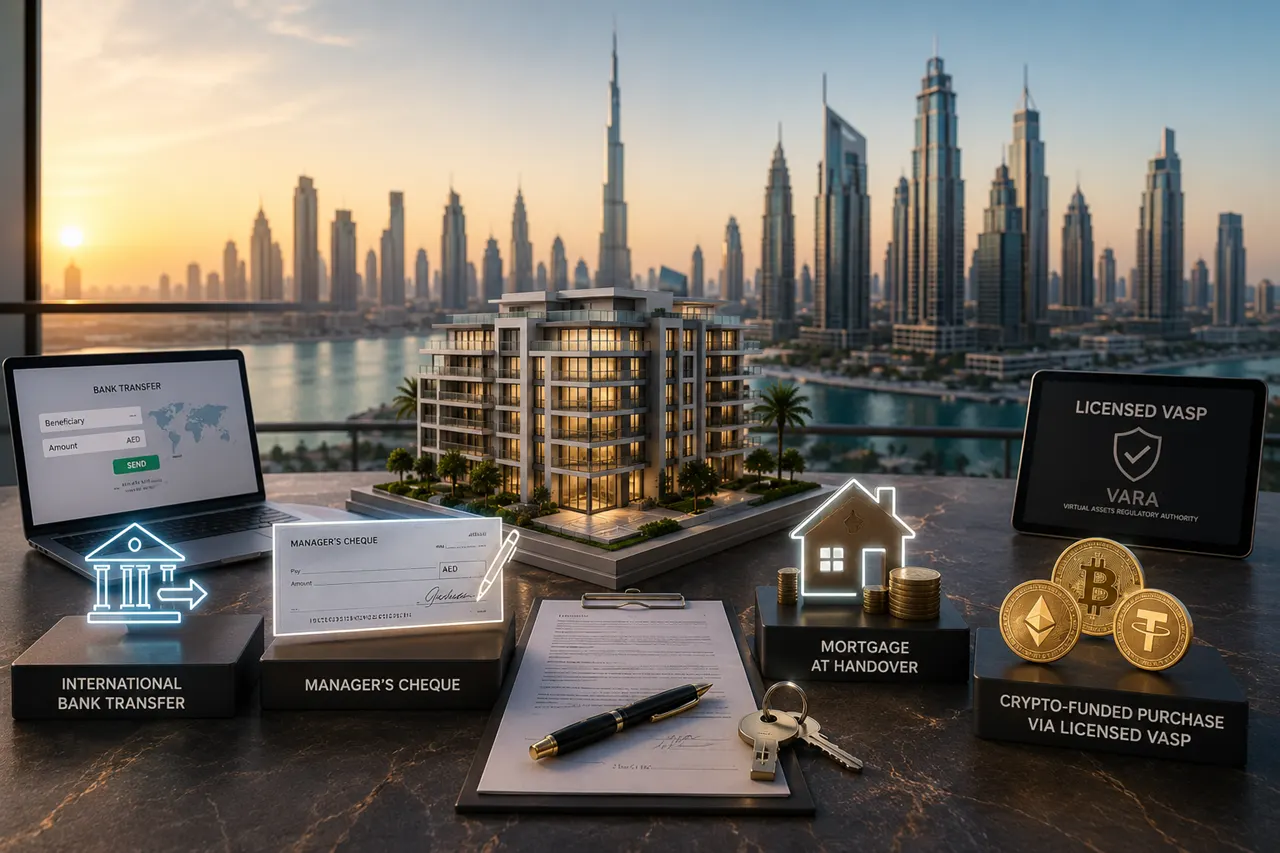
Dubai property settles in AED through four legal routes: bank transfer, manager's cheque, mortgage at handover, or crypto through a licensed exchange. This guide covers payment plans, fees, compliance, FX costs, and timing.
Direct advisor access. Every payment question answered personally, never by a call center.
Payment Methods
Every Legal Way to Pay for Dubai Property
Two-thirds of all property bought in Dubai today is off-plan, and that changes how the money moves. A ready purchase settles in one sitting. An off-plan purchase is paid in stages over years, often from abroad and in a foreign currency, while the rules around each payment keep tightening.
Whatever currency your funds start in, the property is sold and registered in AED. The DLD recognises four ways to get the money there, and most off-plan buyers combine them: an international wire for the construction milestones, then possibly a mortgage for the balance at handover.
International Bank Transfer
The default for foreign buyers: a SWIFT transfer from your home bank straight to the project escrow account, taking 2 to 5 business days and USD 25 to 75 in flat bank fees, with the FX spread on top. Off-plan, you repeat it 8 to 12 times, so the provider you choose compounds. Use it for: every milestone. Cost layer: FX 1 to 3% plus SWIFT fees.
Manager's Cheque
A guaranteed cheque issued by a UAE bank from a UAE account. Off-plan, it usually appears only at booking if you sign in Dubai, and again at handover for any final balance. It clears the same day with no FX exposure at the moment of payment. Cost: AED 25 to 75 ≈ USD 7 to 20 per cheque, up to AED 200 ≈ USD 54 at premium tiers.
UAE Mortgage at Handover
The bank pays the remaining balance, typically 20 to 40% of the price, directly to the developer once the unit is ready. Residents can borrow up to 80% LTV, non-residents typically 50 to 65%, and approval takes 4 to 8 weeks. Cost: a 0.25% registration fee with the DLD plus AED 290 ≈ USD 79 admin, plus bank fees.
Crypto Through a Licensed VASP
Under Federal Decree-Law No. 6 of 2025, crypto is the source of funds and settlement is always in AED. A VARA-licensed exchange or OTC desk converts your BTC, ETH, USDT, or USDC and settles dirhams into escrow in 24 to 72 hours. Cost: 0.5 to 1.5% conversion, often cheaper and faster than banking for stablecoin holders.
Which Method Fits Your Profile
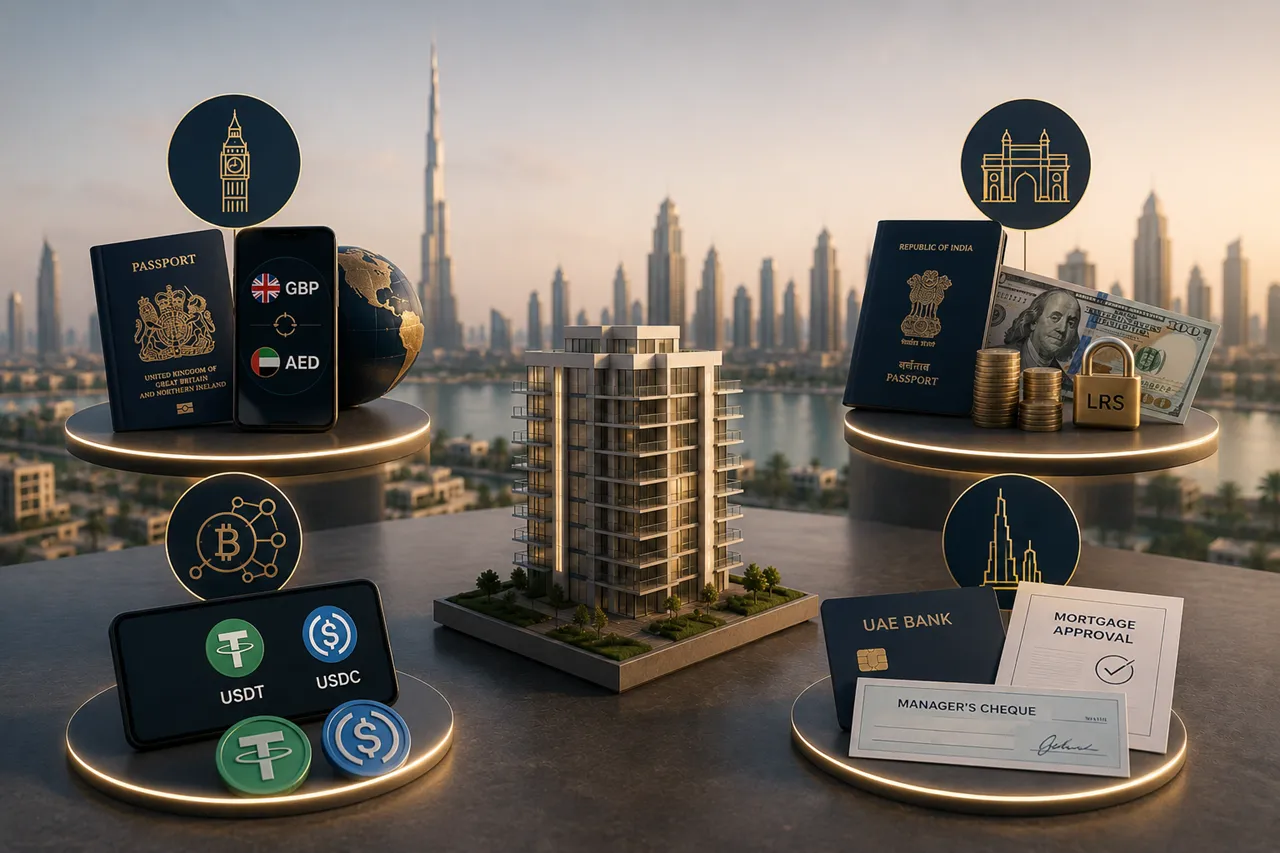
London First-Time Off-Plan Investor
Funds in GBP, no UAE account yet, and an AED 1.5M to 3M ≈ USD 408K to 817K unit on a 60/40 plan over 4 years. Path: open a multi-currency account at Mashreq Neo or Wio before the SPA, lock the GBP-AED rate with a forward contract through OFX or Currencies Direct, and wire each milestone 7 to 10 days early. Estimated saving against a retail-bank approach: GBP 8,000 to 14,000.
Mumbai Buyer Within the LRS Limit
USD 250,000 per person per year under the Liberalised Remittance Scheme, targeting an off-plan villa of AED 5M ≈ USD 1.36M or more. Path: buy as a couple to reach USD 500K a year, add qualifying dependants' quotas, and choose a 60/40 plan over 5 years with a 4-year post-handover plan so payments spread across tax years. Lock forwards on the predictable installments.
Crypto-Native Investor
Large USDT or USDC holdings, little traditional banking, and a preference for speed. Path: confirm crypto acceptance in writing before the SPA, because it changes between projects, payment stages, and compliance requirements, then route every milestone through a VARA-licensed VASP and settle in 24 to 72 hours.
Dubai Resident Upgrading to Off-Plan
Earning in AED and moving from a ready home to a new off-plan unit. Path: pay early milestones from AED savings or the sale of the current property, secure a UAE mortgage commitment 6 months before handover for 60 to 80% of the final balance, and use a manager's cheque for the down payment at SPA signing.
Rules Every Payment Follows
Sold and registered in AED
Paid into the project escrow account
No separate agent commission off-plan
DLD 4% fee, often absorbed by the developer
Oqood registration approx AED 3,000 ≈ USD 817
Funds sent from an account in your own name
Escrow is mandated under Law No. 8 of 2007, and the developer can draw on it only as independent engineers verify each construction milestone. How that protection works in practice is covered in the Dubai escrow account guide. Since the Direct Payment Rule of February 2026, third-party transfers are no longer accepted.
Why Strategy Matters
Why Off-Plan Payment Strategy Matters More Than Buyers Expect
A ready buyer makes one large transfer. An off-plan buyer makes ten or twelve over 5 to 10 years, and each one carries an exchange rate, a compliance check, and a deadline. Two buyers signing for the same AED 2.5M ≈ USD 681K unit can end up AED 80,000 to 150,000 ≈ USD 21,784 to 40,844 apart, most of it lost quietly to FX spreads and compliance delays.
The largest avoidable cost in an off-plan purchase is not a fee. It is the spread on every installment, repeated for the life of the plan.
The Compounding FX Spread
Retail banks take 1.5 to 3% on a USD-to-AED conversion. Across 12 installments on a USD 700K off-plan purchase, that is USD 10,000 to 21,000. Specialist FX brokers work at 0.3 to 0.6% with the same destination, the same compliance, and the same speed.
Currency Risk Over the Plan
If your home currency weakens against the AED, every later installment costs more. Buyers paying in GBP, INR, RUB, or TRY have seen installments inflate 10 to 25% over the construction window in recent cycles. A forward contract locks today's rate for the whole schedule, and most buyers do not know it exists.
The Direct Payment Rule
Since February 2026, funds must leave an account in the buyer's name and land in the developer's escrow account exactly as published on the DLD record. Wires from a relative's, a company's, or a lawyer's account are rejected, and 30-day default clocks start running.
The Compliance Freeze
A wire that fails an AML check can sit frozen for 14 to 30 days. Against a hard SPA deadline, that delay can trigger penalties of 5 to 10% of the unit price, or in extreme cases the cure-period process under Law No. 19 of 2017.
Off-Plan and Secondary: Two Payment Worlds
Payment Timing
Off-plan: 2 to 10 years. Secondary: a single transfer.
Where Funds Are Held
Off-plan: the project escrow account, released as milestones are verified. Secondary: paid direct to the seller.
Buyer's Agent Commission
Off-plan: zero, paid by the developer. Secondary: 2% of the price, plus VAT on the commission.
Down Payment
Off-plan: 5 to 20%. Secondary: typically 10% at MOU signing.
Registration
Off-plan: Oqood, then the Title Deed at handover. Secondary: the Title Deed directly, issued in 1 to 2 hours.
FX Strategy
Off-plan: a forward contract plus tranched conversions across the plan. Secondary: one optimised conversion at the right moment.
A secondary deal completes in one sitting at a DLD-registered trustee office: both parties attend in person or by POA, manager's cheques change hands, and the 4% DLD fee is paid on the spot. Off-plan buyers carry the stronger protection, with escrow refunds on a failed project governed by Decree No. 33 of 2020. This guide leads with off-plan because it dominates the market and its payment journey is longer; a secondary purchase follows the same logic, compressed into one day.
Payment Plans
Off-Plan Payment Plans: How the Structure Works
The payment plan is the most important number in an off-plan deal, ahead of the price per square foot and ahead of the brand. The right plan can turn a stretched purchase into a comfortable one, so read the structure before you fall for the floor plan.
60/40
60% during construction and 40% on handover. The most common structure for mid-market and premium projects from Emaar Properties, Sobha Realty, and similar developers.
70/30
70% during construction and 30% on handover. Less friendly upfront, and often offered with a price discount.
80/20
80% during construction and 20% at handover. Popular for ultra-luxury projects with longer construction periods.
50/50
50% during construction and 50% on handover. Common on projects with shorter timelines of 18 to 24 months.
Post-Handover Plans
Typically 20 to 60% of the price extends 2 to 8 years past handover, often at 1% per month. The developer effectively becomes your lender, with no bank and no interest, against a slightly higher headline price.
Construction-Linked or Time-Linked
Construction-Linked
Payments are released only when an independent engineer certifies a milestone: foundation complete, structure topped out, MEP installation, finishing. If construction stalls, your payments pause. This is the safer structure.
Time-Linked
Payments fall due on calendar dates, quarterly or twice a year, whatever the progress on site, so you may keep paying while construction is delayed. Ask the developer in writing which structure applies, because the answer changes your exposure.
5% of the total project value stays in the escrow account for one full year after handover to cover defects found in the first year of occupancy. If the developer does not fix the defects you log through property snagging in Dubai, the retention is paid out to repair them. It is one of the strongest post-handover protections in the Gulf and one of the most underused buyer rights.
Fees and Savings
Every Fee You Pay on an Off-Plan Purchase
Off-plan fees look very different from the 6 to 8% quoted for ready transactions. Structured correctly, an off-plan purchase runs closer to 4 to 5% of the price all-in. The figures below use a sample off-plan apartment at AED 2.5M ≈ USD 681K.
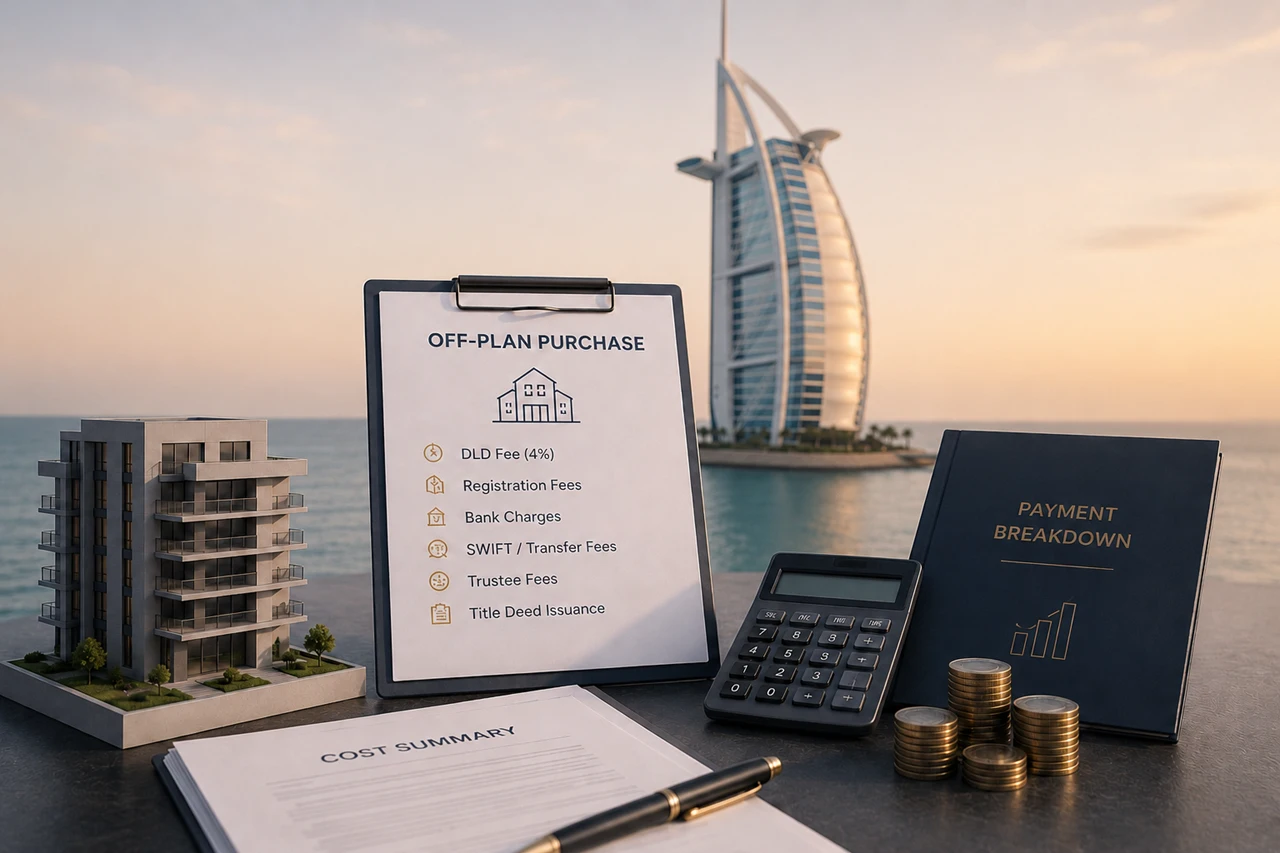
DLD Registration Fee: 4%
AED 100,000 ≈ USD 27,229, paid to the Dubai Land Department. Legally the buyer's obligation, but on off-plan launches developers very often absorb it as a sales incentive, as a full waiver or split 50/50.
Oqood Registration
Approx AED 3,000 ≈ USD 817. The off-plan registration at the DLD, which confirms your interim ownership rights and is your evidence of purchase until the Title Deed is issued at handover.
Currency Exchange Spread
0.3 to 3% across the plan, and the largest hidden cost. On a USD 680K equivalent paid in 10 to 12 installments, a retail bank at 1.5 to 3% against a specialist broker at 0.3 to 0.6% is a gap of USD 8,000 to 18,000.
SWIFT and Bank Fees
USD 25 to 150 per transfer: fixed charges on each milestone, multiplied across the plan.
Title Deed Issuance
AED 580 ≈ USD 158, paid at handover when ownership moves from Oqood to permanent title.
Mortgage Registration
Only if you finance at handover: 0.25% of the loan plus AED 290 ≈ USD 79. On an AED 1.5M ≈ USD 408K mortgage, that is AED 4,040 ≈ USD 1,100, paid once.
Agent commission, NOC fees, and VAT are missing from this list because none of them applies to a standard off-plan residential purchase. Residential property is zero-rated for VAT under Federal Decree-Law No. 8 of 2017; the 5% rate applies only to commercial property and certain serviced apartments.
Four Ways to Cut Your Payment Costs
Use a Specialist FX Broker
Across 10 milestones on a USD 700K unit, the spread alone decides whether you keep USD 15,000 or hand it to a bank. OFX, Wise, Currencies Direct, and MTFX work at 0.3 to 0.6%. Set one up before the first milestone and use it for every installment.
Lock a Forward Contract
A forward freezes today's rate for a future settlement, sometimes years out, and neutralises currency movement over a 5-year plan. Most specialist brokers charge no upfront premium. For TRY, INR, RUB, or ZAR buyers it is close to essential: a 15% currency move during construction can wipe out years of appreciation.
Match the Plan to Your Cash Flow
A 60/40 with a 4-year post-handover plan ties up less capital than a 70/30 without one. The return on capital you do not have to wire today often outweighs the small premium on extended plans, so run the numbers before assuming the cheapest headline plan is the cheapest plan.
Time Your Conversions
Most milestones have a 30-day window. Converting at a good rate two weeks early instead of on the deadline can move thousands, and a pre-funded multi-currency account at Mashreq Neo, Wio, or ADCB makes that possible.
Not sure which FX route or plan structure suits your currency and timeline? Ask me about FX and payment plans on WhatsApp
Compliance and Crypto
The Compliance Checks That Decide Whether Your Wire Lands
Every milestone is a fresh chance for a wire to be held, queried, or returned, so off-plan buyers meet compliance again and again. The answer is to prepare the paperwork once and reuse it for every installment.
KYC Documents
A passport copy, proof of current address, and sometimes a tax residency certificate or home-country tax ID. UAE banks ask once at the start of the relationship and rarely again.
AML Source of Funds
Above AED 1M ≈ USD 272K, which covers most off-plan units, expect payslips and an employer letter, audited accounts and dividend statements, sale documents, inheritance certificates, or portfolio statements. An AED 10M ≈ USD 2.72M villa faces scrutiny an AED 1.5M ≈ USD 408K apartment never sees.
The Direct Payment Rule
Funds must leave an account in the buyer's name and arrive in the developer's escrow account exactly as registered with the DLD, with no third-party transfers and no corporate intermediaries. The rule aligns Dubai with FATF standards and is enforced without discretion at the trustee office or the developer.
Country Transfer Rules
India
USD 250,000 per person per year under the Liberalised Remittance Scheme, with spousal pooling to USD 500K per couple and dependants' quotas on top. Above the annual cap, spread the milestones across tax years.
UK, US, EU, Australia, Canada
No transfer limits, but standard reporting thresholds apply, such as FinCEN reporting above USD 10K in the US. Documentation at the UAE end is the same whatever the origin.
Russia, Türkiye, Iran, Lebanon
Banking restrictions can apply at both ends. A UAE bank account opened in advance, or in some cases a crypto VASP route, is often the only practical path.
File source-of-funds documents with your receiving UAE bank or the developer's compliance team before each milestone wire arrives. Pre-clearance can take 7 to 14 days off a compliance hold.
Paying With Crypto: What Is Allowed
Source of Funds, Not Currency
The AED is the UAE's only legal tender and virtual assets are not currency. Your BTC, ETH, USDT, or USDC goes to a VARA-licensed VASP, is converted, and reaches escrow in dirhams. The DLD registers the unit in AED, always.
Stablecoins Dominate
USDT and USDC remove volatility during the 24 to 72 hour conversion window. A buyer paying in BTC can lose 5% between booking and settlement; a buyer in USDT does not.
The Licensed-VASP Requirement
Sending crypto to a developer's or seller's own wallet outside a licensed setup is not recognised for property purchases and raises AML red flags that can freeze the deal. Route it through a regulated provider and check it on the VARA public register first.
Speed and Cost
Each milestone can settle in 24 to 72 hours against 5 to 10 days for international wires, at 0.5 to 1.5% conversion, which is often cheaper than a retail bank's FX spread.
Crypto acceptance changes between developers, projects, unit types, and payment stages, and compliance can vary with nationality and source of funds. Confirm the exact process in writing before signing the SPA, because verbal approval from a sales agent often fails at AML review.
Problems and Fixes
The Six Payment Problems That Derail Off-Plan Deals
Each of these happens, and each has a defined way out. The earlier you act, the more of your position you keep.
Wire Stuck in Compliance
Funds have left your account but are not in escrow after 5 or more business days, almost always a hold at the receiving or a correspondent bank. Get the SWIFT reference, escalate it to the developer's finance team, and send source-of-funds documents straight away. Most holds clear in 7 to 14 days once documents are in.
Missed Milestone Payment
Under Law No. 19 of 2017, the developer notifies the DLD, which serves formal notice and grants a 30-day cure period to pay, restructure, or settle. Only after it expires can the developer start termination, and the escrow framework still protects your earlier payments.
Project Cancelled or Developer Bankrupt
Cases go to the Special Tribunal for Unfinished and Cancelled Real Property Projects, set up under Decree No. 33 of 2020, and refunds come from the project's ring-fenced escrow account. How much the developer may retain depends on how far construction had progressed at cancellation.
Handover Delayed
Standard SPAs allow a delay tolerance, typically 12 months past the original handover date. Beyond that, compensation can be pursued through the Real Estate Regulatory Agency at the Dubai Land Department or, in severe cases, the Special Tribunal. The 5% retention also gives you leverage, because a late developer wants it released quickly.
Unit Does Not Match the SPA
File a complaint with the Real Estate Regulatory Agency and document everything: the original brochure, the SPA specification sheet, and photos and video of the delivered unit. A material downgrade without your written consent gives grounds for compensation or, in extreme cases, a refund.
FX Losses Across the Plan
Remedies are limited, but partial recovery is possible if a bank misquoted a rate or executed a forward contract badly. Keep every quote, transcript, and confirmation, escalate through the bank's complaints process, and in larger cases go to the UAE Central Bank's Consumer Protection Department.
Timeline and Checklist
The Off-Plan Payment Timeline, From Booking to Handover
The payments run alongside the legal stages of the purchase, from EOI and SPA to Oqood and the Title Deed, which are set out in buy property in Dubai step by step. In order, the money moves like this.
Day 0: EOI Signed
An Expression of Interest with the developer or broker. Refundable in some cases and not in others, so confirm it in writing.
Days 7 to 30: SPA and Booking
The SPA is signed and the first installment, typically 5 to 20% of the price, is wired into the project escrow account. Oqood registration follows shortly after.
Months 1 to 48: Milestones
Each milestone wire leaves 7 to 14 days before its deadline, with source-of-funds documents pre-filed and a forward contract converting at the locked rate if you use one.
During Construction: Checks
Independent engineers verify each milestone. Buyers can usually request site visits, with notice and at limited frequency.
Handover Minus 6 Months: Mortgage
If you are financing, start the UAE mortgage application now. Approval takes 4 to 8 weeks, and pre-approval lets the bank pay on time.
Handover Day: Final Payment and Keys
The final installment, typically 20 to 40% of the price, is wired or paid by the mortgage bank. The snagging inspection takes place, defects are logged, and keys are released.
Title Deed Issued
Oqood converts to the Title Deed, the permanent registration in your name.
Post-Handover Plan: Installments
On a 1% monthly post-handover plan, payments continue 2 to 8 years after you move in.
Handover Plus 12 Months: Retention
Once the developer has resolved the defects logged during the snagging period, the 5% retention is released from escrow.
Nine Checks Before You Sign the SPA
Escrow account matches the DLD record
Delay, default, and specification clauses read
Source-of-funds documents pre-filed
Quotes from at least two FX brokers
Construction-linked or time-linked, in writing
Crypto VASP checked on the VARA register
A 14-day buffer on every milestone
Show unit and brochure photographed at signing
Every promise written into the SPA
Never accept a payment instruction that is not the escrow account on the DLD record. Verbal agreements carry no legal weight in Dubai property disputes, so anything a developer or sales agent promises belongs in the SPA itself.
Payment Guide Library
Dubai Property Payment Guides
Each guide below takes one payment route or cost in depth, from the first wire to the last cheque at the trustee office. For buying, protection, the Golden Visa, and handover, my Dubai real estate guide library covers the rest of the journey.
International Bank Transfer to Dubai
SWIFT and IBAN details, the real cost of a transfer, timing, compliance holds, and country rules.
International Bank Transfer Guide
Manager's Cheque for Dubai Property
Off-plan and resale cheque schedules, buying without a UAE account, and the mistakes that stall a transfer.
Manager's Cheque Guide
Buying Dubai Property With Crypto
The legal framework, nine steps from wallet to Title Deed, costs, and tax on both sides of the conversion.
Crypto Property Payment Guide
Dubai Property Buying Costs
Every fee from the DLD transfer to trustee, mortgage, legal, and ongoing costs, with a worked example.
Buying Costs GuidePlanning Your Off-Plan Payment Strategy?
Tell me your currency, your budget, and the payment plan on offer, and I will show you how to route each milestone so less is lost to FX spreads and compliance delays.
FAQs
Dubai Property Payment Frequently Asked Questions
No. The agent's commission on an off-plan unit is paid by the developer. This is a major structural difference from secondary-market sales, where the buyer pays a 2% commission separately.
No. Residential property in the UAE is zero-rated for VAT under Federal Decree-Law No. 8 of 2017. The 5% VAT rate applies only to commercial property and certain serviced apartments, not to standard residential off-plan units.
Yes. Crypto is permitted as a source of funds. The settlement is always in AED: your BTC, ETH, USDT, or USDC is converted by a VARA-licensed exchange or OTC desk. Select Dubai developers accept crypto-funded off-plan property purchases.
Not strictly. You can wire funds directly from your home-country bank to the developer's escrow account. A UAE multi-currency account is strongly recommended, however, because it lets you time conversions and pre-fund installments at favorable rates.
Legally, the buyer is responsible. In practice, developers frequently absorb the DLD fee as a sales incentive, either as a full waiver during launch periods or as a 50/50 split.
Oqood is the off-plan registration certificate issued by the Dubai Land Department, confirming your interim ownership rights before the title deed is issued at handover. The registration fee is approximately AED 3,000 ≈ USD 817.
Under Law No. 19 of 2017, the developer notifies the DLD of your default. You receive a formal 30-day cure period to pay, restructure, or settle. Only after that period expires can the developer initiate termination, and even then the escrow framework protects most of your prior payments.
Cases go to the Special Tribunal for Unfinished and Cancelled Real Property Projects (Decree No. 33 of 2020). Refunds come from the project's escrow account, with the amount depending on how far construction had progressed at cancellation.
Off-plan mortgages are capped at 50% LTV, so most off-plan buyers pay the construction milestones from their own funds and take a UAE bank mortgage at handover for the remaining balance, typically 20 to 40% of the price. UAE residents qualify for up to 80% LTV; non-residents typically 50 to 65%.
5% of the total project value remains in the escrow account for one year after handover. This protects buyers against post-completion defects: if the developer fails to fix snagging issues, the retention is paid out to cover repairs.
Standard SWIFT transfers take 2 to 5 business days. Add another 7 to 14 days if your wire is held for compliance review. Specialist FX brokers using local payment networks can settle in 1 to 2 days for major currencies.
Introduced in February 2026, the rule requires that funds for any property purchase originate from a bank account in the buyer's name and land in a UAE account in the registered owner's name. For off-plan, that is the developer's escrow account exactly as registered with the DLD. Third-party transfers are no longer accepted.
Your Advisor
Tohid Fetrat
For any questions about your real estate investment, message or call me directly. You will always reach me personally, never a call center or sales team.